DAC7 on Vinted: when the platform reports your sales
DAC7 is an EU rule under which a platform such as Vinted passes a seller's data to the tax authority when the seller completed at least 30 transactions or was paid more than EUR 2,000 in a calendar year. It is a reporting duty of the platform, not a new tax. Check your own numbers with the calculators below.
Last verified:
What DAC7 is and when it applies to a seller
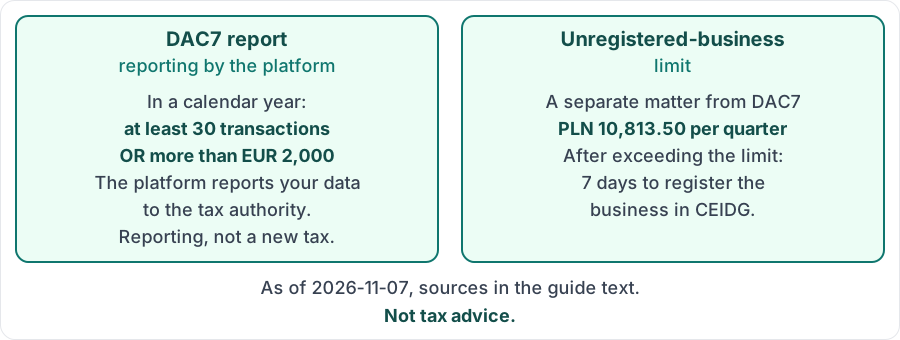
According to the Polish Ministry of Finance, a platform reports a seller to the tax authority (DAC7) when it enabled at least 30 transactions or paid out more than EUR 2,000 in a calendar year. One condition is enough.
According to the Ministry of Finance, the reporting duties impose no new taxes and do not change how income is taxed. Appearing in a report does not mean you have to pay tax.
The unregistered-business limit
This is separate from DAC7. According to biznes.gov.pl, the quarterly revenue limit for an unregistered business in 2026 is PLN 10,813.50 (225% of the minimum wage of PLN 4,806). After exceeding it you have 7 days to register in CEIDG.
Whether selling counts as a business depends on its nature, not on thresholds alone. If in doubt, ask KAS or a tax adviser.
Check your own numbers
The calculators below compare your numbers with the thresholds and the limit. They are a helper, not a decision on your tax obligations. You can compile your yearly sales with the guide "How to download your Vinted monthly statement".
Sources
DAC7 thresholds and no new taxes: Ministry of Finance, "Co warto wiedzieć o dyrektywie DAC7", https://www.gov.pl/web/finanse/co-warto-wiedziec-o-dyrektywie-dac7. The thresholds come from that Ministry page; podatki.gov.pl, "DPI (Digital Platform Information)", https://www.podatki.gov.pl/podatkowa-wspolpraca-miedzynarodowa/dpi-digital-platform-information, confirms no new taxes but words the thresholds ambiguously.
The PLN 10,813.50 limit and 7 days to register: biznes.gov.pl, "Działalność nierejestrowana i inne rodzaje działalności, których nie traktuje się jak działalności gospodarczej", https://www.biznes.gov.pl/pl/portal/00115.
Sources last verified: 7 November 2026. This guide is not legal or tax advice. Rules change, so if in doubt consult KAS or a tax adviser.
Check your numbers
Below the DAC7 thresholds.
DAC7 thresholds: 30 transactions or more than EUR 2000.
Remaining to limit: 10,813.50 PLN (Limit used: 0.00%)
Quarterly limit for unregistered business (Poland): 10,813.50 PLN
Vintlyze
FAQ
- What are the DAC7 thresholds?
- According to the Ministry of Finance, a platform reports a seller to whom it enabled at least 30 transactions or paid out more than EUR 2,000 in a calendar year. One condition is enough.
- Does reporting mean I owe tax?
- No. The Ministry of Finance states that DAC7 imposes no new taxes and does not change how income is taxed. The report only passes information to the tax authority.
- What is the unregistered-business limit in 2026?
- PLN 10,813.50 of revenue per quarter, per biznes.gov.pl. After exceeding it you have 7 days to register in CEIDG.
- Are DAC7 and the unregistered-business limit the same thing?
- No. DAC7 is about the platform reporting data, while the limit is about when selling must be registered as a business. The two calculators on this page show them separately.